 Login
 Register

Credit After a Short Sale — The Honest Comparison to Foreclosure
Posted on 28. Sep, 2026 by ctlms in Blog, My Blog, Short Sale, foreclosure
“Doesn’t a short sale look better on my seller’s credit than a foreclosure?” I get some version of this question from listing agents and attorneys almost every time a file gets referred to me, usually because the seller asked them first and they want to give a good answer. It’s a fair question. I wish I could just say yes. The honest answer is closer, and a lot more useful, than that.
Do credit scores actually treat a short sale differently than a foreclosure?
Not the way most people assume. A credit scoring model doesn’t have a category called “short sale” and a separate one called “foreclosure.” It scores what actually gets reported to the credit bureau about the account: paid as agreed, settled for less than the full balance, charged off, ninety-plus days late, and so on. A short sale and a foreclosure usually get reported as some version of “not paid in full,” coming off what was probably a clean payment history before the trouble started. The label on the closing paperwork doesn’t change what the algorithm sees. What changes the score is the derogatory mark itself.
So how big is the hit, really?
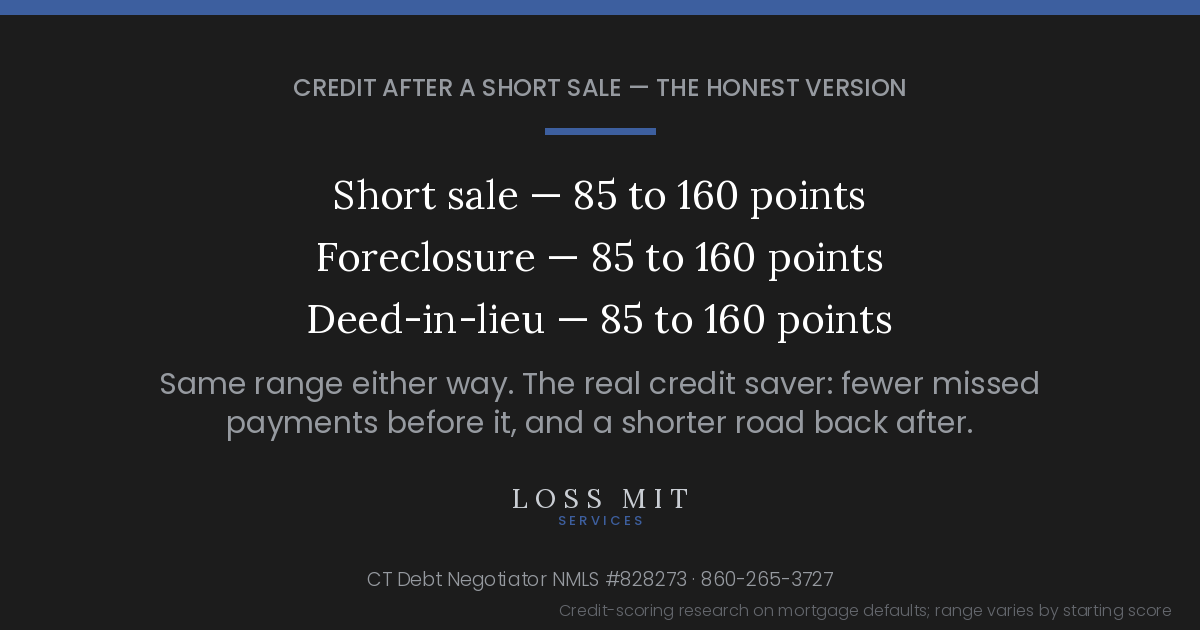
Bigger than most sellers expect, and close to the same either way. Credit-scoring research on mortgage defaults puts the drop at roughly 85 to 160 points, and that range applies whether the account closes as a short sale, a foreclosure, or a deed-in-lieu. Where you land in that range depends mostly on where you started. A seller sitting at 780 loses more, in raw points, than a seller sitting at 640 — the higher the score, the more room it has to fall. I tell every referring agent this up front, because the seller is going to hear it from someone eventually, and I’d rather it be on day one than from a lender six months from now.
Where does the real credit saving come from?
Here’s the part nobody explains to the homeowner, and it’s the whole reason the timing of the referral matters more than anything I do on the file once I have it.
The short sale itself is one derogatory entry. Every missed mortgage payment leading up to it is another one. Thirty days late gets reported. Sixty days late gets reported. Ninety, a hundred and twenty, each one is its own mark on the report, and each one stacks on top of the last. By the time a seller has ridden it out for a year and then finally calls somebody, the short sale is landing on top of twelve months of lates, and the score at the end reflects all of it.
Now compare that to the seller who gets a file to me while they’re still current, or one payment behind. The short sale still hurts. It still lands somewhere in that 85 to 160 range. But it’s landing on a clean history instead of a year of missed payments, and the score at the end is in a completely different place. Same short sale, very different result. The fewer missed payments on the report, the smaller the total hit.
That is the honest version of “a short sale is better for your credit.” It isn’t better because of what it’s called. It’s better because a seller who deals with it early takes one hit instead of thirteen. Being proactive is the credit saver. The short sale is just the vehicle.
What about qualifying for a mortgage again?
This is the second real advantage, and it points in exactly the same direction.
- Fannie Mae cuts the wait roughly in half. A conventional buyer needs 7 years after a foreclosure to qualify again, or 3 years with documented extenuating circumstances. After a short sale, that number drops to 4 years standard, or 2 years with extenuating circumstances. Same credit hit, half the wait.
- FHA is 3 years after either one. FHA doesn’t distinguish much between a short sale and a foreclosure on the standard timeline — both are a 3-year wait.
- FHA has a zero-wait path, and it rewards the proactive seller. If your seller’s mortgage payments and every other monthly debt — credit cards, car loan, student loans, all of it — were current for the full 12 months before the short sale closes, FHA doesn’t require any waiting period at all. That’s a real advantage, and it’s the one most agents have never heard of. Notice who qualifies for it: the seller who stayed current. The same seller who took the smaller credit hit.
The advice that costs your seller both
Here’s where I have to say the uncomfortable thing out loud, because I see this go wrong. Somewhere along the way, somebody tells the homeowner to stop making the mortgage payment during the short sale process — sometimes it’s framed as “it’ll make the file move faster,” sometimes as “you won’t need the money anyway once it closes.” Every missed payment that follows is another mark on the report, and the first one takes the FHA zero-wait path off the table. Nobody explains that trade to the seller at the time. I do, every time it comes up, because it’s the difference between your seller buying again next year and your seller buying again in three, with a lower score when they get there.
[story — a referred file where the seller had been told to stop paying months before it reached me, and what that cost them on both the score and the zero-wait path. Fill in or delete before publishing.]
One more thing that moves the needle
Whether the file closes with a deficiency balance or without one. A short sale negotiated to a full release, with no money still owed on paper, tends to land a little softer than one that reports a balance still outstanding. That’s one more reason how a short sale gets negotiated matters, not just that it happened instead of a foreclosure.
The takeaway
A short sale does not spare your seller’s credit the way the old sales pitch claims. The score drop lands in roughly the same range as a foreclosure — 85 to 160 points, worse for higher starting scores — and anyone telling a seller otherwise is setting them up for a bad surprise later. What actually limits the damage is getting there early: fewer missed payments before the short sale means a smaller total hit, and it keeps the FHA zero-wait path and the shorter Fannie Mae timeline in play. That’s the pitch that holds up, because it’s the true one.
Tell your seller the real version. A short sale isn’t a credit-repair strategy. Getting the file to me early is the closest thing to one.
Send me the address and the approximate payoff. I’ll tell you within a day whether it’s worth pursuing, and what the road back looks like for that seller’s loan type.
As always, feel free to reach out to me with any questions.
Sean Wilder
Loss Mit Services
860-265-3727
CT Debt Negotiator NMLS #828273
Loss Mit Services is a dba of Accredited Home Services, LLC · CT Debt Negotiation License DN-828273
Commission on a Short Sale — What Lenders Allow, and How the Reduction Actually Gets Negotiated
Posted on 21. Sep, 2026 by ctlms in Blog, Foreclosures, My Blog, News, Real Estate, Short Sale, foreclosure
“Am I actually going to get paid on this?” I get that question from agents all the time, usually about two minutes into the first phone call about a short sale listing, and I’d much rather you ask me on day one than find out the answer on the settlement statement in month five. So this post is the honest version, the one you’d get if you called me.
Do lenders cut commissions on short sales?
Yes. Not always, and not nearly as often as the 2009-era horror stories would have you believe, but it happens, and anyone who tells you it never happens is selling you something. What I want to do here is explain WHY it happens, because once you understand the why, you know exactly when to worry and when not to.
Start with who’s paying you. On a normal sale the seller pays the commission out of their equity. On a short sale there is no equity. Every dollar on that settlement statement, your commission included, comes out of the net that goes back to the investor who owns the loan, and that investor is already taking a loss. The banks don’t do short sales to help people, they do short sales to help themselves, and “help themselves” means recovering more than they’d expect to recover by foreclosing. So they have rules for what they’ll allow to come off the top, and the rules depend on who owns the loan. Who owns the loan is the first thing you need to know on any short sale, and this is one more reason why.
What do the big investors actually allow?
Here’s where the real numbers live, and they’re better than most agents expect.
1. Fannie Mae. The Fannie Mae Servicing Guide (section D2-3.3-01, if you want to look it up) lists the transaction costs a servicer can deduct from the sale price on a Fannie Mae short sale. Real estate commission is on the list, described as “customary for the market,” capped at 6% of the sales price.
2. Freddie Mac. Freddie put out a bulletin back in August of 2009 telling its servicers they could no longer condition approval of a short sale on cutting the listing broker’s commission, as long as that commission was 6% or under. Above 6%, the servicer is required to renegotiate it down to 6%. That rule has been the practice on Freddie files ever since.
3. FHA. HUD’s pre-foreclosure sale program, which is what an FHA short sale is called, allows a real estate commission of up to 6% as well.
So on the three biggest buckets of loans in Connecticut, a market-rate commission is an allowable cost and, in my experience, it usually survives the approval intact. That’s the good news, and it’s the part the 2009 stories leave out.
Where do the cuts really happen?
Three places, and after more than 2,000 of these I can tell you they’re pretty predictable.
1. Portfolio lenders and private investors. A local bank or credit union that kept the loan on its own books, or a private investor who bought the note at a discount, doesn’t have to follow anybody’s guide. Their “guideline” is whatever the person reviewing the file thinks is reasonable that day. Some are perfectly fair. Some see the commission as the easiest number on the page to trim. You don’t know until you ask, and I ask early.
2. Second mortgages and other junior liens. This is the big one. The second mortgage holder is often being asked to release a five- or six-figure lien for a few thousand dollars, and they know it. They can’t do much about the first mortgage’s payoff. They can’t do much about the taxes. So when they go looking for a place to squeeze, they look at the commission. It’s not personal. It’s just the only line on the statement they think they can move.
3. Any file where the net comes back a little short. This is the one that catches agents off guard. The valuation comes in, the investor runs the numbers, and the offer nets them a few thousand dollars less than their minimum. Somebody has to give. The buyer might come up a little. The seller, by definition, has no money to bring. So the negotiator on the lender’s side looks down the settlement statement and lands on the commission. This is the moment I’m talking about when I say I’ll tell you it’s coming before it comes. A good negotiator sees the net gap when the valuation lands, not when the approval letter shows up.
What changed with the buyer-agent side?
Since the NAR settlement took effect in August of 2024, buyer-broker compensation isn’t offered through the MLS the way it used to be. A lot of agents ask me how that plays on a short sale. The honest answer is that from the lender’s chair, nothing changed. The lender approves what’s on the settlement statement. If the seller is paying a buyer-broker fee, it shows up as a seller-paid cost, and the lender is looking at the total that comes off the top, however it’s split between the two sides. Write it up cleanly, put it where it belongs, and the total is what gets measured against the ceiling.
So here is the question to ask any short sale negotiator, licensed or not, before you refer a client: how exactly do you get paid, and where on the settlement statement does it land? A straight answer to that question is worth more than any promise about approval rates.
One settlement statement
I’ll say this every time commission comes up, because it’s the whole reason a commission can turn into a surprise. Every lienholder on the file gets the same settlement statement with the same numbers. The first mortgage, the second, the HOA, the tax collector, the town. If the first sees one commission figure and the second sees another, you don’t have a short sale, you have a problem that will surface at the worst possible moment. Same numbers to everybody, one statement, is how we run every file, and it’s how your commission stays what it was approved to be.
The takeaway
Lenders do cut commissions on short sales, but not randomly. On Fannie Mae, Freddie Mac and FHA loans, a commission up to 6% is an allowable cost and usually survives. The cuts come from portfolio lenders, junior liens, and files where the net comes up short, and all three of those are visible early to someone who’s looking. Know who owns the loan. Ask your negotiator how they get paid. Insist on one settlement statement. Do those three things and commission stops being the thing you find out about last.
Send me the address, the approximate payoff, and who services the loan. I’ll tell you within a day whether it’s worth pursuing, and what the commission picture usually looks like on that kind of loan.
As always, feel free to reach out to me with any questions.
Sean Wilder
Loss Mit Services
860-265-3727
CT Debt Negotiator NMLS #828273
Loss Mit Services is a dba of Accredited Home Services, LLC · CT Debt Negotiation License DN-828273
The Expired Listing That Was Never Actually Priced — Why the Cuts Stopped at the Payoff
Posted on 31. Aug, 2026 by ctlms in Blog, Foreclosures, My Blog, News, Real Estate, Short Sale, foreclosure
I want you to try something this week. Pull up your expired listings from the last year — yours, or the expireds you’re prospecting — and look for one specific pattern: the house sat for months, took two or three price reductions, and then the reductions just stopped. Not at a round number. Not at a market number. At a very specific number. And if you go look up the mortgage balance on that property, you’ll find out exactly why the cutting stopped where it did.
I see this constantly, and most agents walk right past it.
Why do price reductions stall at a weird number?
Because that listing was never priced to the market in the first place. It was priced to the payoff.
Here’s how it happens, and no one in the transaction is being dishonest — it’s just incentives doing what incentives do. The seller owes what they owe. When the agent sits down at the listing appointment and suggests a price, the seller does the math in their head: list price, minus commission, minus conveyance tax, minus the payoff… and if that math goes negative, they can’t sign. They don’t have the money to bring to closing. So every pricing conversation on that listing quietly hits a floor, and that floor has nothing to do with what buyers will pay. The agent may not even realize it’s happening — the seller just keeps saying “I can’t go any lower than that,” and the agent hears a stubborn seller instead of an underwater one.
Then the market votes. Showings slow down, feedback comes back on price, the reductions start — and they stop cold the moment the next cut would put the seller underwater at the closing table. The listing rides out the rest of the agreement at a price the market already rejected, and it expires.
The market doesn’t care what the seller owes. And the seller can’t take what the market is offering. That gap has exactly one fix, and it is not another six months on the MLS at the same number: somebody has to negotiate with the lender.
So then you ask, “why would the bank ever take less than they’re owed?”
I get this question every single time, and the answer is the most important thing in this whole post: the banks don’t do short sales to help people. They do short sales to help themselves.
When a lender evaluates a short sale, they’re running a math problem. On one side: approve the sale today and take the net proceeds. On the other side: foreclose, pay the legal costs, wait out the process, take the property back, pay to secure and maintain and insure it, then sell it as a bank-owned property — usually in worse condition than it’s in right now, because vacant houses don’t age well. When they run those numbers, the approved short sale frequently nets them more. That’s the entire reason the process exists. Nobody at the bank is doing anyone a favor — they’re protecting their own recovery, and the homeowner and the agent happen to benefit from it. I’ve worked on thousands of these files and I can tell you the lender’s math is the engine of every single one.
What do you actually say to that expired seller?
This is where the expired listing becomes a referral trigger instead of a dead lead. The homeowner has usually concluded the house “can’t sell.” That’s not what happened. The house couldn’t sell at a price that clears the debt. Those are two different problems, and the second one has a process. A few things to keep straight when you have that conversation:
1. Be honest about the timeline. A short sale typically runs 4 to 6 months from start to close, and the lender’s approval alone commonly takes 60 to 120 days before you even get to the closing window in the approval letter. If someone tells you short sales wrap up in a couple of months, they’re working off a very old playbook. The seller who hears the real timeline up front stays in the deal; the one who was promised a fast close walks in month three.
2. Make no promises about approval. Nobody can guarantee a lender says yes — not me, not anyone, and you should be suspicious of anybody who talks like they can. What an experienced negotiator can do is look at the loan type, the lienholders, and the numbers, and tell you whether the file is worth opening. That’s an honest answer, and sellers respect it.
3. Keep the seller current on their obligations to their lender. Nothing in this process involves ignoring the servicer or the mail. Whether and how a seller pays anything is between the seller, their lender, and their own advisors — the short sale conversation is about resolving the debt through a sale, not avoiding it.
4. Know what you’re checking before the appointment. The payoff versus realistic value is the whole ballgame. If you can get even an approximate mortgage balance and compare it against what the price history already told you about value, you’ll know whether you’re walking into a normal relisting or a short sale before you ring the doorbell.
And one thing NOT to do: don’t relist it at the same price and hope. The market already voted. Hope is not a pricing strategy.
Why the agent who explains this usually gets the relisting
Think about what that homeowner has heard so far: months of silence, then an expired notice, then a stack of postcards from agents promising better marketing. You’d be the first person to walk in and correctly name the actual problem — the debt, not the marketing. In my experience the agent who says “your house didn’t fail, your payoff is bigger than your value, and there’s a process for that” is usually the one holding the new listing agreement when it’s over. Not because of a slicker presentation — because they told the truth about a problem everyone else misdiagnosed.
The takeaway
An expired listing where the payoff exceeds any realistic list price is not a failed listing. It’s a short sale that never got started. The tell is sitting right in the price history: reductions that stall at a suspiciously specific number. Find those files, check the balance, and have the honest conversation — real timeline, no promises, a process instead of a diagnosis of failure.
If you’ve got one of these — expired, price cuts that stopped cold, a payoff that doesn’t fit the value — send me the address and the approximate payoff. I’ll tell you within a day whether it’s worth pursuing.
As always, feel free to reach out to me with any questions.
Sean Wilder
Loss Mit Services
860-265-3727
CT Debt Negotiator NMLS #828273
Loss Mit Services is a dba of Accredited Home Services, LLC · CT Debt Negotiation License DN-828273
Connect with Us


Bio

Sean Wilder started in the pre-foreclosure business in 2007. Previously he enjoyed successbusiness in the transportation industry, real estate investing and as a licensed Realtor. Sean brought the same determination and work ethic that lead to great success in his previous businesses to Loss Mit Services based in East Windsor, CT. His focus, combined with his drive to succeed, have been essential to his success as one of the area's top short sale negotiators.
Known for finding creative ways to overcome hurdles and never ending persistence; Sean, believes in the power of team. Sean and his team are in the trenches everyday, plowing through challenges and objections while negotiating with various lenders, and finding solutions to difficult problems. It is this daily experience that brings Loss Mit Services consistent success and provides them the knowledge to share.
Sean belongs to a number of industry groups and associations that allow him to collaborate, share, learn, teach and stay updated on the latest changes in the pre-foreclosure industry at the federal, state, local and lender specific levels.
Effective Oct 1, 2009 all debt negotiation companies that offer loan modification, short sale, or foreclosure rescue services needed to be licensed by the CT Dept of Banking. Sean and his company Loss Mit Services were the 1st to be awarded the Debt Negotiation License NMLS # 828273 which can be verified at the CT Dept of Banking Website by Clicking Here. In addition, effective Oct 1, 2011 Debt Negotiators were required to also be licensed Mortgage Loan originators and Sean also has received this license, NMLS# LO-831853.

Recent Comments